
How Are Partnership Taxes Calculated?
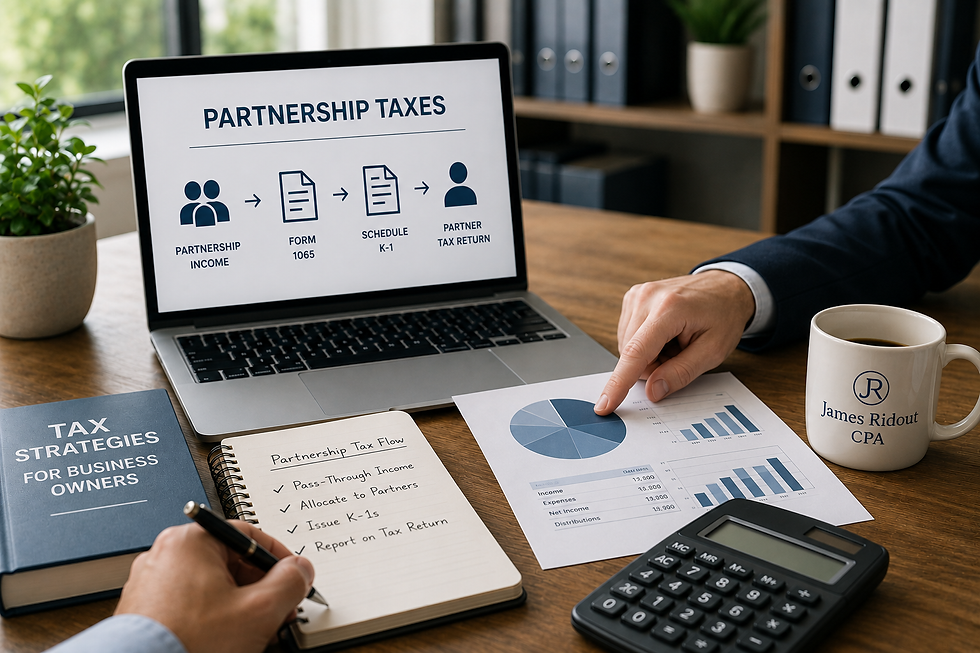
Partnerships are generally treated as pass-through entities for federal income tax purposes. This means the partnership typically reports its financial activity on a business tax return, while each partner reports their share of the partnership’s taxable items on their individual or business return.
Understanding how partnership income is allocated and reported is important for both accurate business tax preparation and personal tax planning.
How Is a Partnership Taxed?
A partnership generally files an annual federal information return rather than paying federal income tax directly on its profits.
The return reports the partnership’s:
Income
Expenses
Deductions
Gains and losses
Other relevant tax items
These amounts are then allocated among the partners according to the partnership agreement and applicable tax rules.
What Is Form 1065?
Most partnerships use Form 1065, U.S. Return of Partnership Income, to report their federal tax information.
Form 1065 provides the IRS with information about the partnership’s operations for the year.
The partnership generally must file this return even though the resulting taxable income is passed through to its partners.
What Is a Schedule K-1?
Each partner generally receives a Schedule K-1 showing their allocated share of the partnership's tax items.
A K-1 can report items such as:
Ordinary business income
Rental income
Interest and dividends
Capital gains and losses
Deductions
Credits
Other separately stated items
Partners use this information when preparing their own tax returns.
How Is Partnership Income Divided?
Partnership income is not necessarily divided simply according to how much cash each partner receives.
Allocations are generally determined by the partnership agreement and must comply with applicable tax rules.
Depending on the partnership structure, different partners may have different ownership percentages, responsibilities, capital contributions, and economic arrangements.
Do Partners Pay Tax on Money They Didn't Receive?
Potentially, yes.
A partner may owe tax on their allocated share of partnership income even when the partnership does not distribute the same amount of cash.
For example, a partnership might retain some profits to fund operations or future growth while the taxable income is still allocated to its partners.
This makes estimated tax planning particularly important for some partnership owners.
How Are Partnership Distributions Taxed?
Cash or property distributed from a partnership is generally treated differently from the underlying allocation of taxable income.
Whether a distribution creates additional taxable income can depend on several factors, including the partner's tax basis in their partnership interest.
This is why distributions should be tracked separately from the income shown on Schedule K-1.
What Is Partnership Basis?
A partner's tax basis generally reflects their investment in the partnership, adjusted over time for various transactions and tax items.
Basis may change because of:
Capital contributions
Allocated income
Allocated losses
Distributions
Certain partnership liabilities
Other adjustments
Basis can affect whether distributions are taxable and whether partnership losses can currently be deducted.
Can Partnership Losses Be Deducted?
Partnership losses may potentially pass through to the partners, but that does not mean every loss can automatically be deducted immediately.
Deductibility can be limited by several tax provisions, including basis limitations, at-risk rules, passive activity rules, and other restrictions.
Losses that cannot currently be deducted may potentially be suspended for future use when applicable requirements are satisfied.
Do Partners Pay Self-Employment Tax?
Certain partnership income allocated to partners may be subject to self-employment tax.
The treatment depends on the partner's role, the nature of the income, and other circumstances.
This can make partnership taxation different from the taxation of shareholders in an S corporation.
Why Accurate Partnership Records Matter
Partnership returns can become complicated when there are multiple owners, changing ownership interests, distributions, contributions, loans, or significant transactions during the year.
Maintaining accurate accounting records helps ensure that income and expenses are properly reported and that each partner receives an accurate Schedule K-1.
Partnership Tax Preparation With James Ridout CPA
James Ridout CPA works with partnerships and their owners to prepare accurate business tax returns, Schedule K-1s, and related tax reporting.
Whether you operate a two-person partnership or a growing multi-owner business, our team can help you understand your filing requirements, organize your financial information, and navigate the tax considerations affecting both the partnership and its owners.
This article is intended for general informational purposes and should not be considered individualized tax, legal, or financial advice. Partnership taxation depends on the business structure, individual circumstances, and applicable tax law.


Comments